Can you make money as an investor eschewing the business press and trusting your own observations and experiences?
Normally I scoff at people who say things like "I'm buying Thomas Cook - people will always go on holiday", completely ignoring the current share price and the company's competitive and financial position. In fact Thomas Cook is down 90% over the last 2 years; people may always go on holiday but they are also free to book with online competitors.
But a walk down the cereal aisle at Tescos this week did give me an investment insight.
I bought Tesco shares quite heavily in January after their first profit warning in 20 years had caused them to fall by 20% or so in a matter of hours. I thought the fall overdone and expected to be quickly up on my investment. It turns out I was wrong about that as the shares have hovered around the same level ever since and even gone lower on occasion.
It was a long term investment of course and I can wait. TSCO yields 4,5% and the significant business that it does outside the UK should ensure that group profits continue to grow and give me a healthy return.
Certainly beats any cash ISA investment I know of.
There is no denying though that Tesco's UK retail core is suffering and its not just the recession. Other supermarkets are doing well and stealing market share. There are problems with non-food and the bosses admit that they have let standards of service and store presentation slide.
But fundamentally it's a question of their prices. They have got used to growing by simply opening more stores and retaining customers with gimicky Clubcard offers.
It has been obvious for some time that Tescos has become an expensive place to shop particularly when compared to Asda. To be fair to the management they recognised this long before the profit warning and acted last year with the Big Price Drop promotion.
The City was lukewarm about the plan and it didn't help much at Christmas when other stores, particularly Sainsburys, won custom with special offers and one off bargains which made Tescos "5p off own-brand cheddar" look a bit weak.
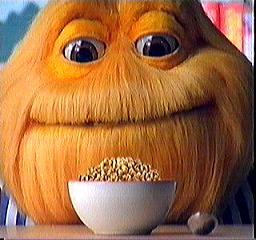
That's where the Honey Monster comes in. I noticed his Sugar Puffs were an eye-catching £1 under the Big Price Drop sign. Looking around I saw a host of other meaningful price falls right through the aisles.
What does that say to you? Management is backing its own judgement and sticking with a strategy that is aimed squarely at the right target - Tesco needs to be genuinely cheaper. Also they have listened to criticism and made the campaign stand out more. Tell'em About the Money! (imagine monster voice)
The news for Tescos has actually been pretty bad this week with an embarassing mice infestation in a London store grabbing the headlines ("Mice refuse to leave sinking ship"). All the articles have trotted out the lines about how Big Price Drop has failed and the company is on the ropes.
But if you take a contrarian view now would be a good time to buy Tescos. All this bad news is in the price and if the company is still holding its market share (down a mere 0.1% this year) while its everyone's favorite whipping boy and when it is still struggling to get its pricing policy right, what will happen when it puts things right - as I think it is - and the press start to pick on someone else?
From our website: Massive tax rises for Spain in 2012
Showing posts with label Tesco. Show all posts
Saturday, March 31, 2012
Wednesday, March 16, 2011
Good news: the FTSE's falling!
For anyone thinking about what to do with their ISA allowance or are just looking for an alternative to the depressing returns available at their local building society, recent stock market events should have given plenty of food for thought. On the face of it, with the FTSE (and most world stock markets) falling, one thought would be - don't bother with shares, they are too risky. Look a bit closer though and you might come to a different conclusion.
The FTSE 100 has had a good run since the financial crisis, up 69% (84% if you include dividends reinvested). Share prices have fallen sharply though over the last few days perhaps on fears that the oil price rise, goepolitical instability and Europe debt fears will drag on markets. The Japan earthquake has taken share prices lower too. That suggests share prices have had a good run and the risks are on the downside going forward.
Maybe, and I don't propose to go into all the arguments here but I would highlight some other bits of recent news from the UK stock market concerning dividends:
** Morrisons announced it would be increasing its divi by 10% for each of the next three years and returning 1 billion £ to shareholders via a share buy back.
** Prudential announced a 20% rise in its dividends
** AMEC, the energy services and engineering company, announced a 50% hike in its dividend
If you focus on the underlying income that shares generate rather than share prices, the news is mostly excellent and actually has been very good over the last decade.
People often make a comparison with share dividend yields and bond or bank deposit interest. Currently you could get 2.5-3% from bank accounts and around 3.5% from the FTSE. The argument goes that shares are risky so they should be yielding considerably more. On that basis you should wait until share prices fall back and yields rise; in the meantime "play safe" in cash.
But I would argue that the comparison is false. Interest on bank deposits is static (or falls when unscrupulous deposit takers quietly lower their rates and hope you don't notice) whereas dividends should rise over time, if you pick shares in the right companies.
As an example, look at Tesco PLC which in 1998 was paying around 4p a share in dividends. Since then the dividends have grown 10% a year on average to stand at around 11p in 2010. Tesco yields around 3.25% but the key point is that if it continues to grow its earnings and dividends by anything like the rate it has achieved in the past, the yield (particularly with dividends being reinvested in more shares) will easily beat interest bearing accounts.
But will companies like Prudential, AMEC and the supermarkets continue to grow particularly if recession returns and some serious global crises unfold? I would argue that certain companies with pricing power (strong brands and competitive positions) and in key sectors (utilities, energy) should continue to grow their earnings even in an uncertain economy. Partly this is because they are good defensive companies we can't live without, and partly because the dividend only gives part of the picture. Back to Tesco - they may pay a dividend just over 3% but actually they earn more than twice that amount and that additional money is invested back into the business to underpin future growth.
So when you see share prices falling remember that it could just mean that a great source of growing income has just got cheaper. This certainly is the view of The Sunday Times Money editor Kathryn Cooper who wrote on Sunday: "high quality blue chips with solid dividend yields have been out of favour for three years; surely their time has come".
Labels:
AMEC,
dividends,
investment,
ISA,
Morrisons,
Prudential,
shares,
Tesco
Subscribe to:
Posts (Atom)